
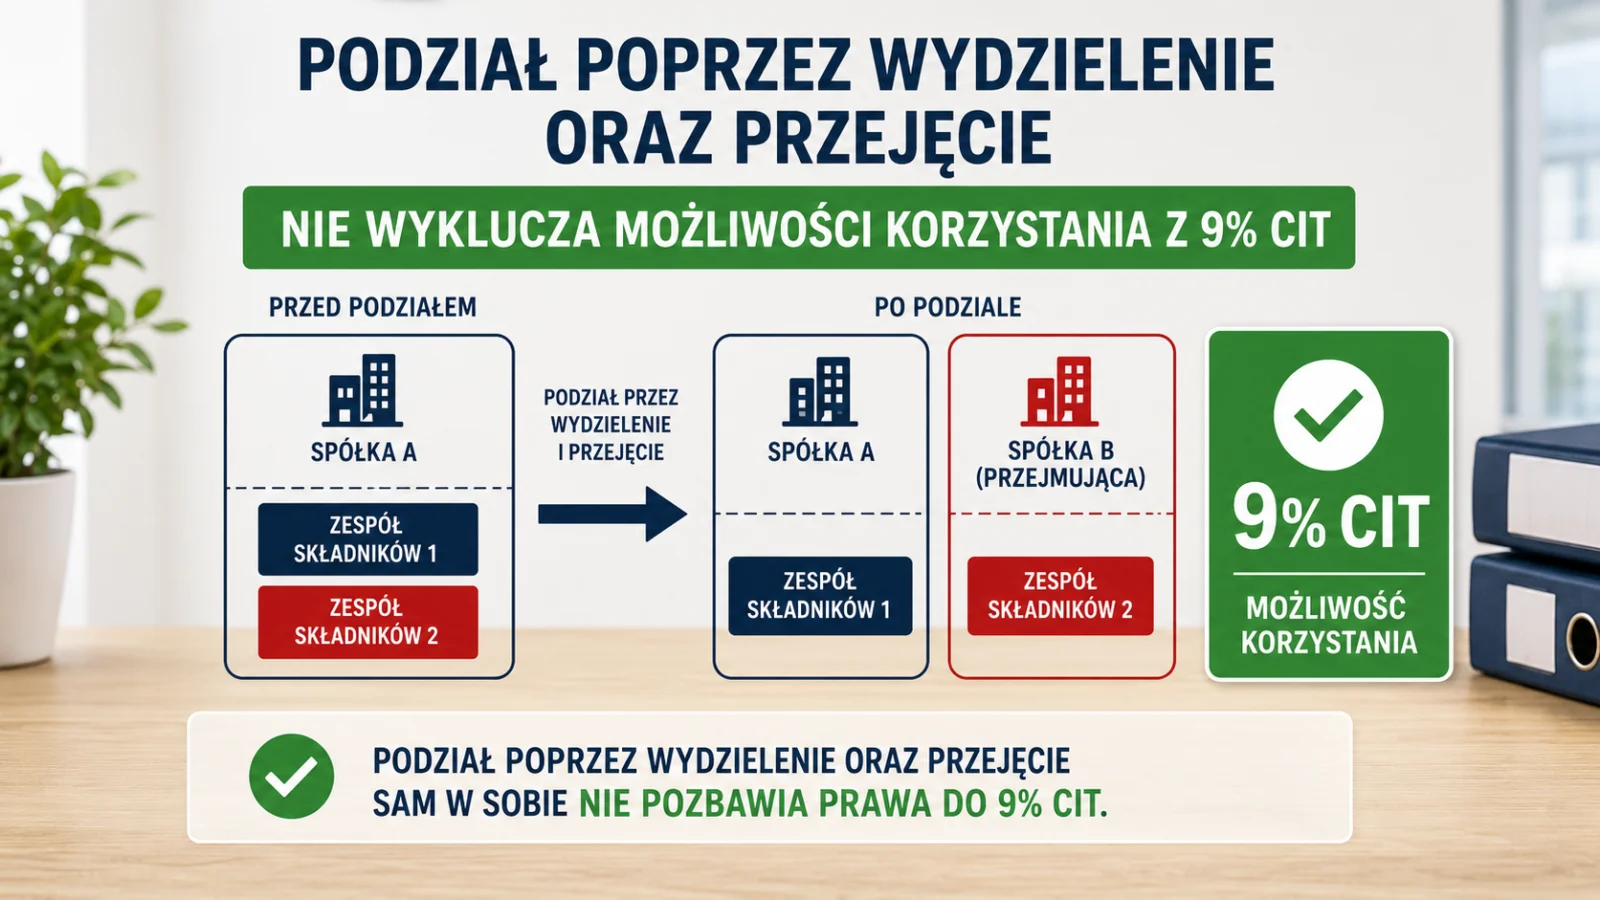
Letter issued by the Director of National Revenue Information on 27 February 2026, reference no. 0111-KDIB1-2.4010.683.2025.1.ANK.
“(…) Applying the above provision to the exclusion concerning the tax rate…”
Letter issued by the Director of National Revenue Information on 27 February 2026, reference no. 0111-KDIB1-2.4010.683.2025.1.ANK.
“(…) Applying the above provision to the exclusion concerning the tax rate…”