
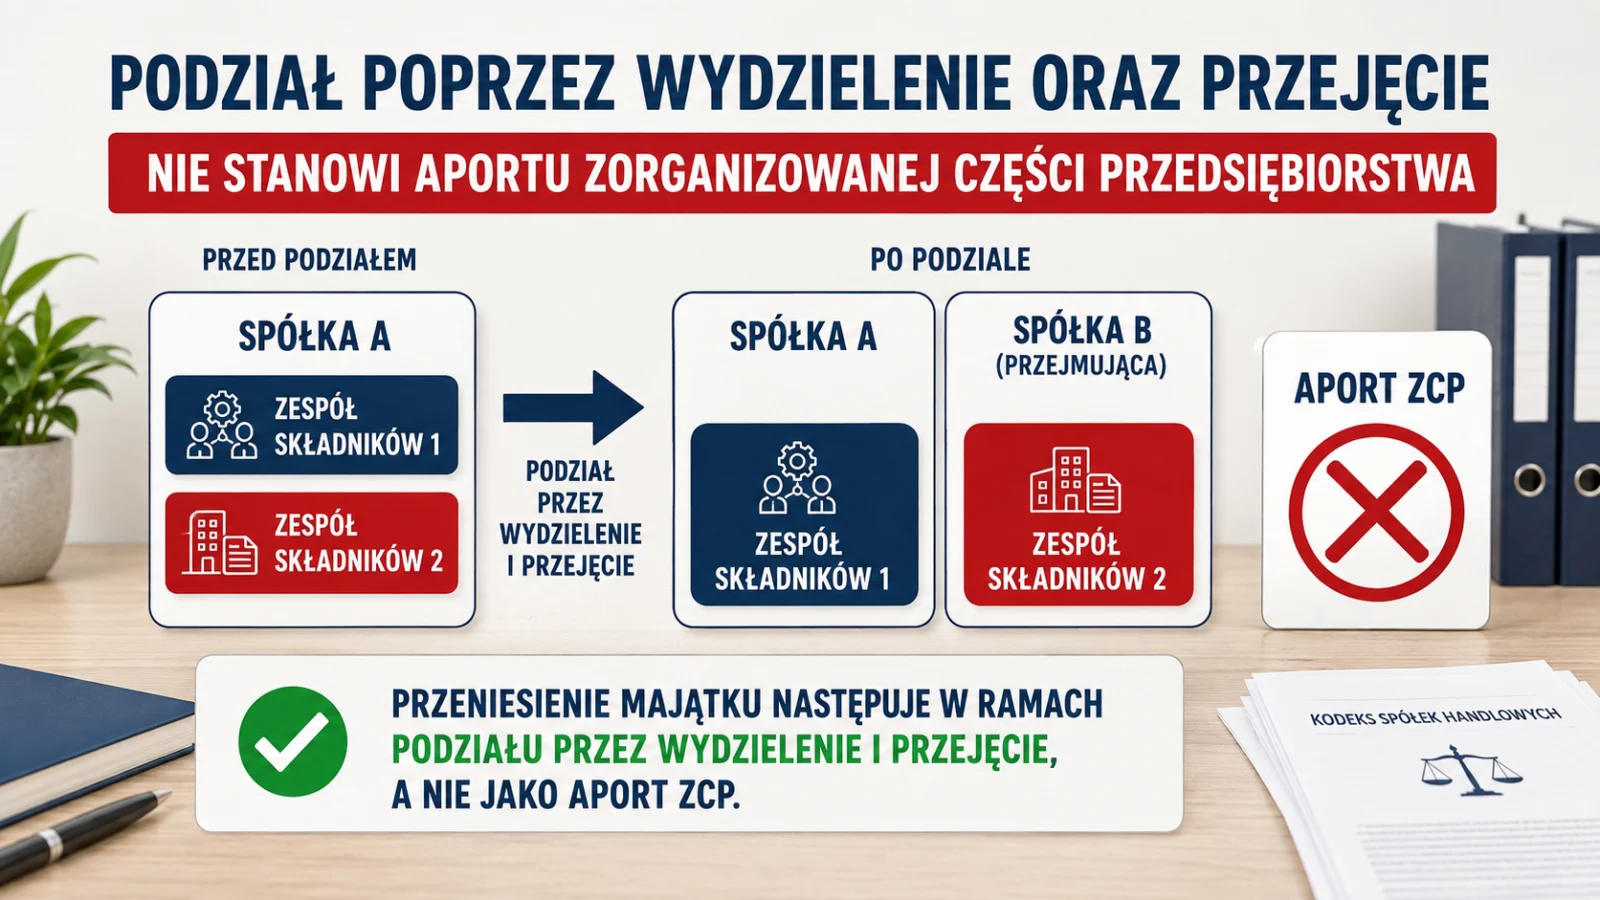
Letter issued by the Director of National Revenue Information on 27 February 2026, reference no. 0111-KDIB1-3.4010.819.2025.1.MBD. “(…) Applying the above considerations to the matter addressed in the application for an individual tax ruling…”
Letter issued by the Director of National Revenue Information on 27 February 2026, reference no. 0111-KDIB1-3.4010.819.2025.1.MBD. “(…) Applying the above considerations to the matter addressed in the application for an individual tax ruling…”